News and Insights
The Numerof 2027 U.S. Healthcare Delivery Outlook

The U.S. healthcare delivery industry enters 2027 facing a familiar set of challenges, but with mounting financial pressures and policy changes that raise the urgency for fundamental change. Persistent staffing shortages, rising operating costs, constrained reimbursement, and the continuing migration of care to lower-cost settings have challenged conventional delivery models for years. What is different now is the prospect of significant disruptions in insurance coverage and Medicaid funding, coupled with intensifying demands from payers, employers, and consumers for greater value. For many hospitals and health systems, incremental improvements will no longer be sufficient.
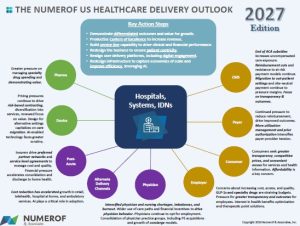
Perhaps the most consequential new development is the growing financial exposure associated with changes in federal healthcare policy. The expiration of enhanced Affordable Care Act premium subsidies increases the risk that individuals will lose coverage or move to less generous plans. At the same time, new Medicaid eligibility requirements and restrictions on state Medicaid financing will put additional pressure on hospital revenues. Work requirements and more frequent eligibility determinations, beginning in 2027, could increase the number of uninsured patients and coverage interruptions. Other Medicaid financing changes will phase in over several years, potentially reducing supplemental payments to hospitals. Together, these developments threaten to increase uncompensated care while weakening an already fragile financial foundation, particularly for safety-net and rural providers.
These pressures come on top of longstanding reimbursement challenges. Medicare payment constraints, continued movement toward site-neutral reimbursement, and the migration of inpatient procedures to outpatient facilities will further pressure traditional hospital margins. Although policymakers and payers continue to promote accountability for cost and outcomes, resistance to at-risk payment arrangements persists. Providers remain reluctant to assume additional financial risk without sufficient confidence in their ability to manage utilization and total cost of care. Meanwhile, more aggressive utilization management and prior authorization requirements are intensifying tensions between payers and providers.
The pressure to control costs is also reshaping the competitive landscape. Employers are increasingly concerned about the affordability, accessibility, and quality of healthcare benefits, with spending on GLP-1 therapies and other specialty pharmaceuticals adding to the burden. Interest in benefit optimization and targeted therapeutic solutions is growing. Consumers, meanwhile, continue to demand convenient access, competitive prices, greater transparency, and better access to their health information. Affordability is becoming an increasingly important determinant of whether and where they seek care.
Alternative delivery models are gaining ground as providers and other market participants seek to reduce costs and improve access. Retail clinics, telehealth, hospital-at-home programs, and ambulatory services continue to expand, while financial pressures accelerate consolidation in post-acute care and greater reliance on home health. Artificial intelligence is becoming an important enabler of these models, as well as a tool for improving efficiency across conventional delivery organizations. However, the challenge is shifting from adopting AI to demonstrating that it produces meaningful improvements in productivity, care delivery, and financial performance.
Workforce challenges remain another persistent constraint. Physician and nursing shortages, geographic imbalances, and burnout continue to strain capacity and increase costs. Physician employment, practice consolidation, private equity investment, and concierge models are reshaping how care is organized and delivered. Hospitals and health systems must strengthen physician alignment while reconsidering the roles, incentives, and operating structures needed to improve performance.
These developments reinforce the need for healthcare delivery organizations to rethink how they create and capture value. Cost reduction remains essential, but cutting headcount and negotiating better prices with suppliers will not be enough. Leading organizations will differentiate their clinical capabilities, strengthen service line performance, and productize Centers of Excellence into offerings that demonstrate superior outcomes and economic value to employers, payers, and patients. They will also redesign care delivery platforms, expand digital engagement, and leverage AI to achieve efficiencies that traditional approaches cannot deliver.
As 2027 unfolds, the distinction between organizations that simply respond to financial pressures and those that fundamentally redesign their businesses will become increasingly important. Success will require a sharper focus on patient centricity, differentiated value, and the ability to translate clinical capabilities into sustainable financial performance.
Given this outlook, what’s next? We recommend these key action steps:
- Demonstrate differentiated outcomes and value for growth.
- Productize Centers of Excellence to increase revenue.
- Build service line capability to drive clinical and financial performance.
- Redesign the business to ensure patient centricity.
- Realign care delivery platforms, including digital engagement.
- Redesign infrastructure to capture economies of scale and improve efficiency,
leveraging AI.
At Numerof & Associates, we support healthcare delivery organizations in reinventing their strategies, processes, structure, and analytics to succeed in our evolving healthcare landscape. From competitive strategy to implementation of new payment and delivery models, we have solutions. Read more about our perspectives and solutions for healthcare delivery and see our case studies.
Need critical insights across the healthcare sector? Check out our 2027 outlook infographics for pharmaceuticals, medical devices and diagnostics, and payers.


